The Real Cost of Holding Your Own Keys: Operational Risks US Traders Systematically Underestimate
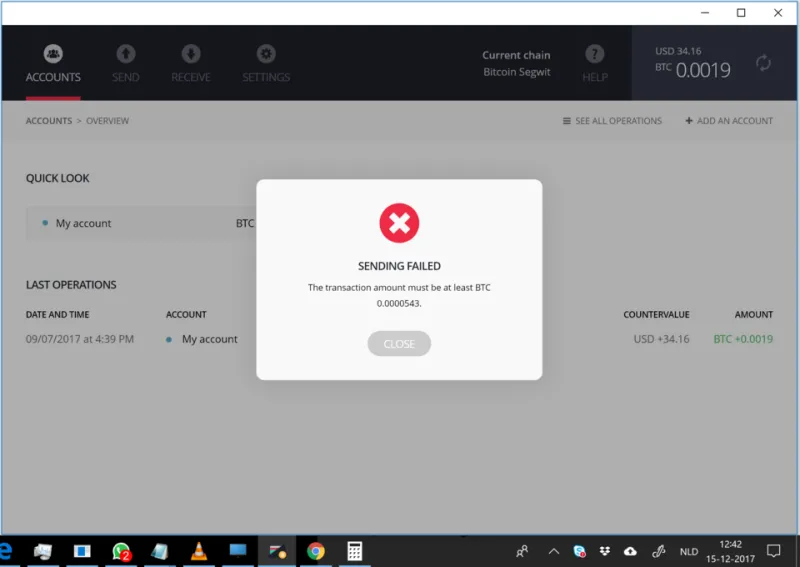
Photo: FlippyFlink, CC BY-SA 4.0, via Wikimedia Commons
The phrase "not your keys, not your coins" has achieved something close to doctrinal status in Bitcoin culture. As a philosophical proposition about ownership and counterparty risk, it contains genuine insight. As a complete risk management framework for US traders operating in 2025, it is dangerously incomplete.
The conversation about Bitcoin custody has been dominated by the risks of delegating control to third parties—exchange collapses, custodial fraud, regulatory seizure. These risks are real and documented. What receives far less systematic attention are the operational risks that self-custody introduces: risks that have quietly claimed a significant and largely unreported share of Bitcoin held by US retail participants.
What the Losses Actually Look Like
Self-custody failures do not generate press releases. They accumulate silently, reported only in Reddit threads, estate disputes, and occasional academic surveys attempting to estimate the volume of permanently inaccessible Bitcoin.
Current estimates suggest that somewhere between three and four million Bitcoin—a figure that represents a substantial fraction of the total supply—is effectively lost. While not all of this can be attributed to self-custody errors by contemporary holders, the category of losses attributable to passphrase forgetting, seed phrase destruction, and hardware failure is measurable and growing.
Among US traders who have attempted self-custody, the most common failure modes follow a consistent pattern.
Seed phrase mismanagement remains the single largest source of permanent loss. The standard 12- or 24-word BIP39 seed phrase provides complete wallet recovery capability—which means it also represents a single point of catastrophic failure. Traders who store seed phrases digitally expose themselves to theft through malware and cloud compromise. Those who store them on paper expose themselves to fire, flood, and simple misplacement. The failure rate on paper storage over a multi-year holding period is higher than most self-custody advocates acknowledge.
Hardware wallet corruption and firmware errors represent a less discussed but operationally significant risk. Hardware wallets are purpose-built security devices, but they are also consumer electronics subject to component failure, firmware update complications, and manufacturer discontinuation. A trader who purchased a hardware wallet from a manufacturer that subsequently exited the market—a scenario that has occurred more than once in the past five years—may find that recovery processes require technical expertise that exceeds their capabilities.
Social engineering attacks targeting self-custody holders have become substantially more sophisticated. Attackers who identify a target as a self-custody Bitcoin holder—information that is increasingly inferable from public on-chain data and social media activity—deploy impersonation campaigns designed to extract seed phrases under the guise of technical support, wallet migration, or security verification. Unlike exchange hacks, which require penetrating institutional security infrastructure, social engineering attacks against self-custody holders exploit individual psychology rather than technical vulnerabilities.
The Inheritance Problem US Traders Ignore
American estate law was not designed with bearer instruments in mind. Bitcoin held in self-custody is, functionally, a bearer asset: whoever possesses the seed phrase controls the coins. This creates a legal and practical inheritance complication that most US self-custody advocates do not address with adequate seriousness.
A trader who holds Bitcoin in self-custody without establishing a documented, legally sound inheritance protocol has, in effect, created a time-limited asset. Upon their death or incapacitation, the coins become inaccessible unless surviving family members or estate administrators can locate and correctly use the relevant seed phrases and hardware. The probability of this occurring without deliberate planning is low.
US estate attorneys with cryptocurrency expertise report that inheritance-related Bitcoin loss is among the most common self-custody failure modes they encounter. Unlike exchange-held Bitcoin, which can be transferred to heirs through standard estate administration processes, self-custody Bitcoin requires technical knowledge that grieving family members frequently do not possess and may not be able to acquire in time to prevent loss.
A Decision Matrix for Custody Selection
The appropriate custody approach for any given trader depends on a structured evaluation of competing risk factors rather than ideological preference. The following framework provides a practical starting point.
Self-custody is likely appropriate when:
- The trader holds a position size that meaningfully exceeds the insurance limits of available regulated custodians
- The trader has the technical background to correctly implement and maintain hardware wallet security
- A documented, legally reviewed inheritance protocol has been established
- The trader's threat model specifically includes regulated custodian failure or regulatory asset seizure
- The trader can commit to a regular review schedule for custody infrastructure
Regulated custodial solutions warrant serious consideration when:
- The trader's position size falls within the coverage limits of FDIC-equivalent crypto insurance programs offered by regulated custodians
- The trader lacks confidence in their ability to maintain seed phrase security over a multi-year holding period
- The trader's estate planning has not addressed digital asset inheritance
- The trader is subject to social engineering risk due to public identification as a Bitcoin holder
- The trader's primary concern is counterparty risk from unregulated exchanges rather than regulated custodians
The Middle Path: Tiered Custody Architecture
For many US traders, the optimal solution is not a binary choice between full self-custody and complete custodial delegation. A tiered approach—allocating a portion of holdings to regulated custodians for operational convenience while maintaining self-custody of a long-term reserve position—distributes risk across multiple failure modes rather than concentrating it in either direction.
This approach does require that the self-custody component be implemented with genuine operational rigor: geographically distributed seed phrase storage, hardware redundancy, and documented inheritance procedures. A tiered custody architecture that applies self-custody standards carelessly to the reserve position achieves the complexity of both approaches while capturing the benefits of neither.
Reframing the Custody Conversation
The ideological framing that dominates Bitcoin custody discourse has served an important purpose: it has educated a generation of traders about the fundamental difference between holding Bitcoin and holding a claim on Bitcoin. That distinction matters.
What it should not do is foreclose a rigorous, individualized assessment of operational risk. The trader who loses their Bitcoin to a forgotten passphrase has not preserved their financial sovereignty. They have experienced a total loss that no exchange collapse could have produced more effectively. Serious capital management demands that this possibility be evaluated honestly and planned for accordingly.